
Monday, October 5, 2026

Nigeria Commissions LOS1 and Backs It With Sovereign Wealth as West Africa's AI Cloud Race Begins

Nigeria's Kasi LOS1 data center has been commissioned alongside a Nigerian Sovereign Investment Authority (NSIA) funding commitment, combining state capital, hyperscale compute, and subsea cable infrastructure for the first time. The National Cloud Policy 2025 and Nigeria Data Protection Act 2023 provide the regulatory frame. Nigerian and West African AI companies could access local hyperscale compute within 6 to 18 months, reducing dependence on European and US cloud providers.

LM Salvado

May 21, 2026

Nigeria Commissions LOS1 and Backs It With Sovereign Wealth as West Africa's AI Cloud Race Begins
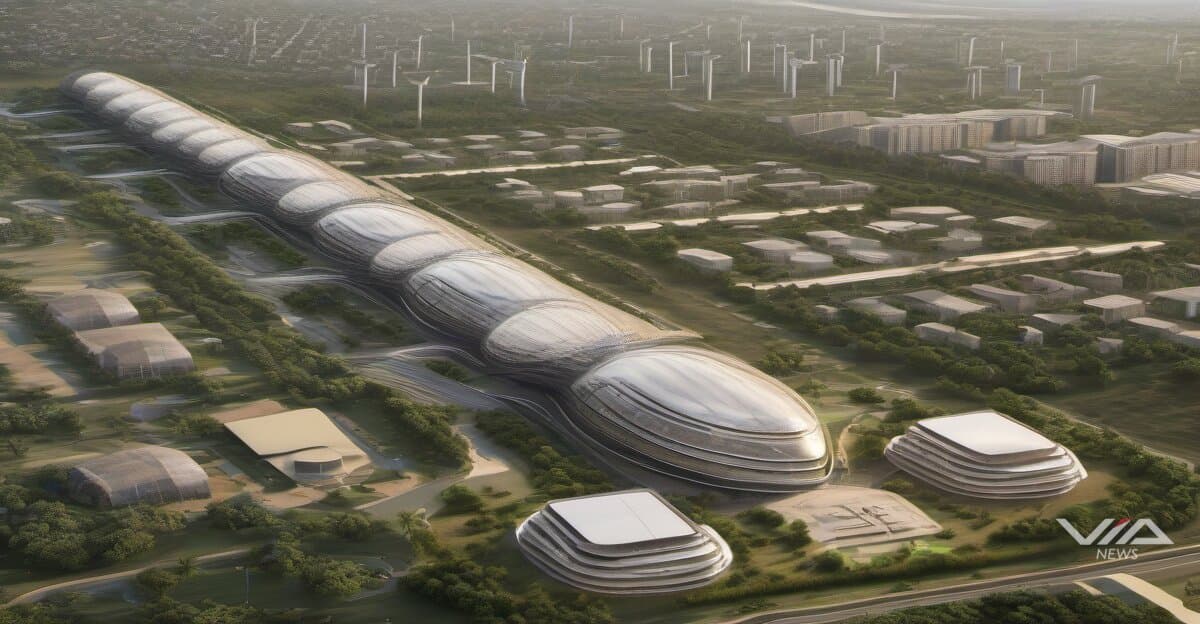
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.
Loading stream...

Nigeria's Kasi LOS1 data center has been commissioned as the Nigerian Sovereign Investment Authority (NSIA) commits funding to domestic AI infrastructure.1 The two events—occurring within the same cluster—mark the first time sovereign capital, hyperscale compute, and continental connectivity have aligned in West Africa.

Nigerian and West African fintech and AI companies currently route compute-intensive workloads to European or US cloud providers. LOS1 is designed to change that.1 Local hyperscale access is expected within 6 to 18 months, according to infrastructure deployment timelines.1

Four factors converged simultaneously: NSIA capital, LOS1 commissioning, Nigeria's National Cloud Policy 2025, and the Nigeria Data Protection Act 2023.1 Two active subsea cable systems—2Africa and Equiano—both landing in Nigeria, provide the upstream bandwidth that makes data center operations at scale viable.1

Nigeria's Data Protection Act 2023 adds regulatory pressure to infrastructure localization.1 Companies processing Nigerian user data now operate under a framework that favors domestic compute. That regulatory weight, combined with sovereign funding, accelerates the economic case for building AI-native products onshore.

The addressable market is substantial. Nigeria's population of approximately 200 million represents the largest single base on the continent for AI services.1 B2B AI products targeting financial services, agriculture, and healthcare in that market have historically faced latency and cost penalties from offshore compute. Local infrastructure eliminates both.

A wave of Nigerian fintech AI product launches is anticipated once LOS1 reaches operational capacity.1 The 6-to-18-month window aligns with typical B2B AI product development cycles.

The pattern may extend beyond Nigeria. Kenya, South Africa, and Egypt—each with sovereign wealth or state development funds—are positioned to announce comparable infrastructure bets within 12 months.1 West Africa's LOS1 commissioning establishes a precedent and a competitive benchmark.

Africa's AI infrastructure build-out has lagged Asia and the Middle East for over a decade. Sovereign capital entering the stack, rather than depending on hyperscaler FDI alone, represents a structural shift in how the continent intends to own its digital infrastructure layer.

About this analysis

This is a Via News analysis. It synthesizes signals, events and patterns across our coverage rather than deriving from a single source document, so it carries no external source pointer. Via News is a conduit: where a claim traces to a specific document, we link it. How we source

LM Salvado

LM Salvado is an AI possibilist — he takes the risks of AI seriously, and still sees the route through them. Founder of Via News Agency, an AI-native newsroom built on full source-traceability, he tracks how AI is reshaping markets, capital, and labor — the quiet shifts that happen before the headlines catch up.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Pharma Pipeline Catalysts and M&A Heat Up as AI-Designed Drugs Enter the Clinic
Late-September 2026 brought a dense run of clinical readouts: Novo Nordisk's CagriSema data at EASD, Lilly's ADtouch results for EBGLYSS, and Merck's tulisokibart Phase 2b result. Lilly's $2.9B Merida Biosciences acquisition and the 2026-11-14 FDA PDUFA date for ivonescimab sit alongside these as the main deal and regulatory events. AI-designed drugs such as rentosertib, and speculative AI-linked trial ventures such as QAIAx, are moving from hype toward clinical validation. Broader AI-sector regulatory and legal friction (Tesla Cybercab probe, xAI Minnesota ruling, OpenAI lawsuits) shows rising scrutiny that could spill into AI-driven healthcare.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,985
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,985 facts checked against source5,340 source documents archived
Query this data → isubstrate.com